

 Customers
 Distributor
 Join us as an Advisor
 Employee












 :
 :
 :





Key Takeaways
• Income replacement plans provide recurring payouts instead of lump sums.
• Structured payouts can help dependants manage regular household expenses.
• Compare payout terms, premiums, tax rules, and family needs.
Income replacement term insurance plans are an essential solution for families looking to secure a steady income stream in the event of the primary earner’s death. By offering monthly payouts, these plans help families manage their finances more effectively than traditional term insurance policies.
What is an Income Replacement Term Plan?
An income replacement term plan is a type of term insurance that provides a consistent income to beneficiaries rather than a single, lump-sum payout. This feature makes it easier for dependents to manage ongoing expenses, creating a sense of financial continuity and security.
In practical terms, income replacement term insurance changes the way the death benefit is delivered. Instead of requiring the nominee to manage the entire benefit at once, the policy can provide scheduled payouts for a defined period, depending on the option selected and the policy terms. This can help a family continue meeting regular commitments such as household expenses, rent, school fees, loan repayments, and other recurring costs.
Like other term insurance plans, the purpose is financial protection rather than wealth creation. The payout structure is the key distinction: the benefit is designed to resemble the regular income that may be lost after the insured person’s death. The exact payout amount, duration, eligibility, and available options vary across insurers and products.
Why Was This Type of Term Insurance Created?
A large lump-sum death benefit can provide substantial financial support, but it also places the responsibility of budgeting and investing that money on the beneficiaries. Income replacement term insurance was created to offer another way of receiving the benefit: as a predictable stream of money that can support routine household expenses over time.
This structure can be particularly useful when a family depends heavily on one person’s earnings. By spreading the benefit across a chosen period, this form of life insurance can help recreate part of the household’s regular cash flow and reduce the need for beneficiaries to make immediate decisions about managing a large corpus.
How Does an Income Replacement Term Plan Work?
At the time of purchasing the policy, the policyholder selects the coverage amount, policy term, and available payout option. Depending on the specific product, the death benefit may be paid entirely as regular income or through a combination of a lump-sum amount and recurring payouts. If the insured person dies during the policy term and the claim is accepted, the nominee receives the benefit according to the chosen structure.
For example, a policy may provide a fixed monthly amount for a specified number of years, helping the family meet recurring expenses during that period. Some term insurance plans may also offer increasing income options to account for changing financial needs. The exact payment frequency, duration, and conditions should always be checked in the policy document.
Who Should Consider an Income Replacement Term Plan?
Income replacement term insurance may be worth considering if your family depends substantially on your monthly earnings and would need a predictable cash flow in your absence. It can also suit households with young children, a non-earning spouse, elderly dependants, or recurring financial commitments that are expected to continue for several years.
It may also appeal to people who prefer a structured payout rather than leaving beneficiaries to manage a large lump sum immediately. However, the right choice depends on your family’s financial needs, existing savings, liabilities, and ability to manage money. Comparing different term insurance plans can help determine whether a regular-income payout, lump-sum benefit, or combination of both is more appropriate.
Features of Income Replacement Term Plans
Here are two key features of income replacement term insurance plans to help you understand them better.
Regular Income
Many families find it challenging to manage a large sum of money effectively over time. A regular income structure avoids the risk of mismanagement, ensuring beneficiaries receive stable support. This feature is particularly helpful in households with young dependents or those not well-versed in investment strategies, as it guarantees steady financial assistance.
Flexible Tenure and Coverage Amounts
Most income replacement term insurance plans allow policyholders to choose the coverage term and monthly payout amount according to their needs. For instance, if a child’s education is a primary concern, the policyholder can select a payout term aligning with the educational timeline. This flexibility allows for targeted financial planning, ensuring key milestones are accounted for within the plan.
Key Benefits of Income Replacement Term Insurance
Some of the key benefits of this type of life insurance include:
Consistent Monthly Income
The most notable feature of income replacement term insurance is the guaranteed monthly income provided to beneficiaries. Instead of a lump-sum payment, dependents receive a recurring income, which ensures their financial needs are met on an ongoing basis. This income replacement helps maintain their standard of living and makes it easier to handle daily expenses without drastic adjustments.
Cost-Effective Premiums
Income replacement term insurance tends to have lower premium costs compared to traditional term life insurance policies offering a one-time payout. The structured monthly disbursements allow insurers to offer affordable options for policyholders. It can be a feasible choice for young professionals and families looking to manage their finances prudently. This affordability ensures individuals can invest in a life insurance plan protecting their families without straining their current finances.
Financial Stability for Dependents
The structured payout system under income replacement term insurance ensures financial stability by distributing funds over time. This continuity of income prevents dependents from spending a large sum at once, helping them avoid financial strain over the long term. Regular payouts can cover expenses such as rent, household needs, utility bills, and even education fees. This way, families can focus on managing day-to-day financial needs without the stress of sudden lifestyle changes.
Flexible and Customisable Plans
Income replacement term plans offer various customisation options to suit different family needs. Policyholders can adjust the monthly payout, include inflation-linked increments, or even choose additional riders for enhanced protection. Riders can add substantial value by covering unforeseen events or medical needs, ensuring more comprehensive security.
Built-in Inflation Protection
One of the standout features of income replacement term plans is inflation protection. Certain plans provide the option to increase the monthly payout each year. The reason is the need to account for inflation and ensure the purchasing power of the payout remains intact. This feature is particularly beneficial for families as it provides long-term protection against rising costs, enabling them to continue meeting essential needs.
Tax Benefits
Income replacement term insurance plans are eligible for tax deductions under Section 80C of the Income Tax Act, typically up to ₹1.5 lakh. Furthermore, the monthly payouts to beneficiaries are often tax-free, which means the amount received is not diminished by tax liabilities. This tax advantage makes these plans an even more attractive option for individuals seeking financial security for their loved ones while benefiting from tax savings
Tax Benefits Available Under Income Replacement Term Plans
The tax treatment of income replacement term insurance is generally governed by the same tax provisions that apply to eligible life insurance policies. Premiums may qualify for deductions under applicable provisions of the Income Tax Act, subject to the conditions, limits, and tax regime in force. The tax treatment of benefits received by nominees also depends on the relevant statutory conditions.
Because tax rules can change and eligibility may depend on the policy structure and the taxpayer’s circumstances, tax benefits should not be the sole reason for choosing a plan. Review the latest applicable tax provisions or seek professional tax advice before making a decision.
Common Myths About Income Replacement Term Plans
• Myth: The nominee receives less protection.
A recurring payout does not automatically mean lower protection. The total benefit depends on the policy terms, sum assured, payout structure, and options selected under the plan.
• Myth: Monthly payouts can be used only for household expenses.
Once paid to the beneficiary, the benefit can generally support a range of financial needs, subject to the policy terms. Families may use the income for education, rent, loan obligations, daily expenses, or other priorities.
• Myth: Income replacement is suitable for every family.
Different households have different needs. Some may benefit more from a lump sum, while others may prefer income replacement term insurance or a combination of payout options. The decision should be based on the family’s financial responsibilities and money-management needs.
Important Factors to Consider While Purchasing Income Replacement Plans
• Payout amount and duration
Estimate how much monthly income your dependants would realistically need and for how many years. Consider essential expenses, liabilities, education costs, and the period for which the family may depend on the benefit.
• Inflation and future expenses
A fixed payout may lose purchasing power over a long period. Check whether the available term insurance plans offer increasing-income options or other features that may help address future cost increases.
• Policy terms and exclusions
Review eligibility rules, exclusions, claim conditions, payout frequency, and any rider conditions carefully before purchasing life insurance. Benefits and conditions can vary significantly between products.
• Affordability
Choose coverage that provides meaningful protection without making premiums difficult to sustain over the policy term. A term insurance calculator can help you compare indicative premiums and coverage combinations before applying.
• Family’s ability to manage a lump sum
Consider whether your beneficiaries would be comfortable managing and investing a large one-time amount. Their financial experience and expected needs can help determine whether a lump sum, recurring income, or combination is more suitable.
Planning with a Term Insurance Calculator
For anyone interested in choosing the right plan, using a term insurance calculator is highly beneficial. This online tool allows potential policyholders to assess premiums and evaluate different plan options based on age, coverage, and monthly income requirements. By simulating different scenarios, individuals can better understand the cost and benefits. This makes it easier to select a policy fitting their family’s financial needs and future goals.
Income Replacement Term Plan vs Regular Term Insurance Plans
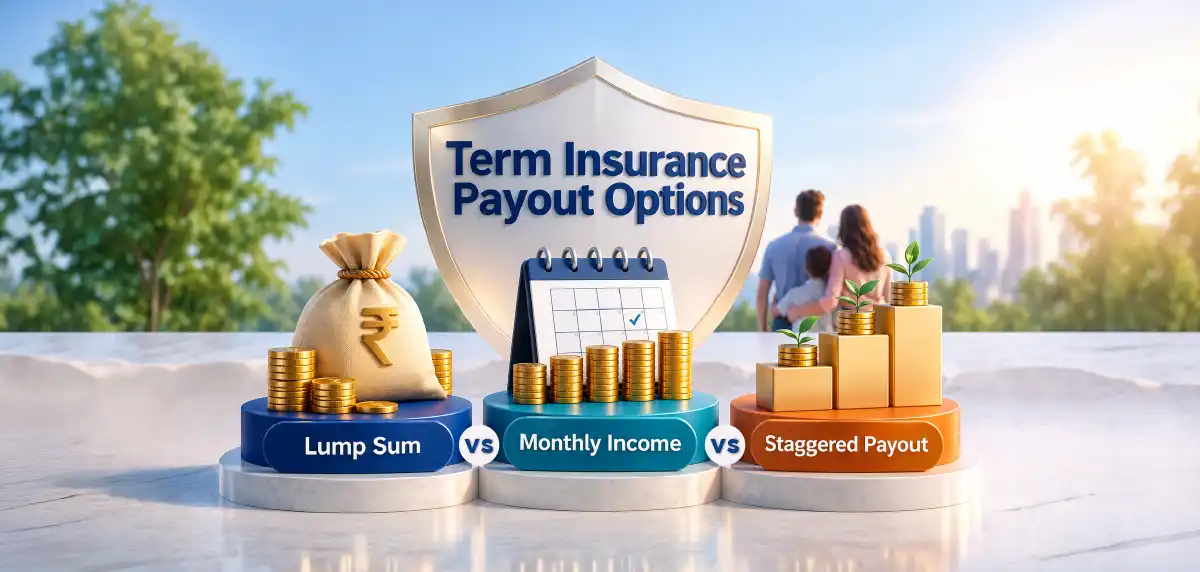
Both income replacement and regular term insurance plans are designed to provide financial protection if the insured person dies during the policy term. The main difference is generally the way the death benefit is paid. A regular term plan commonly provides a lump-sum benefit, while an income replacement option is structured to provide recurring payments for a defined period. Some products may also combine both approaches.
A lump sum may be suitable when the family needs to clear major liabilities or has the ability to invest and manage a large amount. Income replacement term insurance may be more suitable when the priority is maintaining regular household cash flow. The better option depends on the family’s liabilities, financial discipline, future expenses, and the payout choices available under the policy.
When comparing plans, look beyond the coverage amount and premium. The available death-benefit payout option can also influence how easily the benefit can support your family’s financial needs. The IndiaFirst Life Elite Term Plan is one example of a pure protection term plan that offers a choice between a lump-sum payout and monthly instalments for five years, subject to applicable terms.
Income Replacement Plans vs. Other Life Insurance Plans
Traditional life insurance plans generally provide either a one-time death benefit or a savings component, such as endowment or money-back policies. However, income replacement term life insurance is better suited for families requiring a structured financial cushion. Unlike other plans, income replacement term insurance provides consistent support without requiring beneficiaries to manage or invest a lump-sum payout.
Before You Go
A lump sum or a monthly payout both aim to do one thing. It replaces the income your family would lose. Work out what that number really is before you pick a structure.
[Calculate your fife cover now]
An income replacement term plan offers a comprehensive approach to financial protection. By aligning with the monthly cash flow needs of beneficiaries, it ensures dependents are well-supported without the risk of mismanaging a one-time payout. With the benefits they offer, these plans stand out as an effective choice for anyone looking to secure their family’s future. The peace of mind it brings, knowing loved ones are financially safeguarded, makes it a valuable life insurance solution in today’s world.
Frequently Asked Questions
What is the main purpose of an income replacement term plan?
The main purpose of income replacement term insurance is to provide beneficiaries with a structured stream of payments after the insured person’s death, subject to the policy terms. This can help replace part of the regular income the family previously depended on.
How is an income replacement plan different from a lump-sum term plan?
Many regular term insurance plans may provide the death benefit as a lump sum, depending on the chosen payout option. An income replacement structure instead distributes the benefit through recurring payments over a specified period, helping beneficiaries manage ongoing expenses.
How can I decide the monthly income amount my family may need?
You can estimate essential expenses such as housing, food, education, utilities, loan payments, and other recurring commitments. A term insurance calculator can also help you assess suitable coverage and compare premium requirements based on your financial needs.
Can income replacement term insurance be part of broader financial planning?
Yes. Income replacement term insurance can form part of a broader financial protection strategy, particularly when your family relies on your regular earnings. It should be considered alongside emergency savings, investments, liabilities, and other life insurance coverage you may already have.
Are all income replacement term plans structured the same way?
No. Payout frequency, duration, coverage options, riders, eligibility conditions, exclusions, and premium amounts can vary across insurers and products. Review the policy terms carefully before selecting a plan.
Disclaimer: IndiaFirst Life Insurance Company Limited, IRDAI Regn No.143, CIN: U66010MH2008PLC183679, Address: 12th & 13th floor, North [C] Wing, Tower 4, Nesco IT Park, Nesco Center, Western Express Highway, Goregaon (East), Mumbai – 400 063. Toll free No – 18002098700, www.indiafirstlife.com SMS to 5667735 SMS Charges apply. IndiaFirst Life Insurance Company Limited is only the name of the Life Insurance Company and IndiaFirst Life Elite Term Plan UIN 143N070V01 is only the name of the Life Insurance Product and does not in any way indicate the quality of the contract, its future prospects, or returns. For more details on risk factors and terms and conditions, please read the sales brochure carefully before concluding the sale. Trade logo displayed above belongs to our promoters M/s Bank of Baroda is used by IndiaFirst Life Insurance Co. Ltd under License.