

 Customers
 Distributor
 Join us as an Advisor
 Employee












 :
 :
 :





Key Takeaways
Term insurance provides affordable, high-value financial protection for your family during a specified policy term.
When choosing a plan, evaluate the sum assured, policy duration, payout options, riders, claim settlement ratio and flexibility.
Riders such as accidental death, critical illness and waiver of premium can enhance protection based on your specific needs.
Understanding tax benefits, grace periods and changing coverage requirements can help you select a term plan aligned with your family’s financial goals.
Term insurance is one of the simplest yet most effective ways to secure your family’s financial future. Yet, despite the simplicity, it’s essential to understand the key features of term insurance before making a decision. A term plan is a type of life insurance policy providing coverage for a specified term, or duration, typically ranging from 10 to 40 years. These plans offer pure risk coverage, meaning that the insurer pays a death benefit to the policyholder's nominee against the paid premium, in case of an untimely demise during the policy term.
Let’s explore the critical elements to look for in a term insurance plan and understand how they can align with your family’s needs and financial goals.
Key Features of Term Insurance Plans
Understanding the features of term insurance is critical for choosing a policy meeting your family’s requirements. Here are some of the most important features to consider.
Affordable Premiums
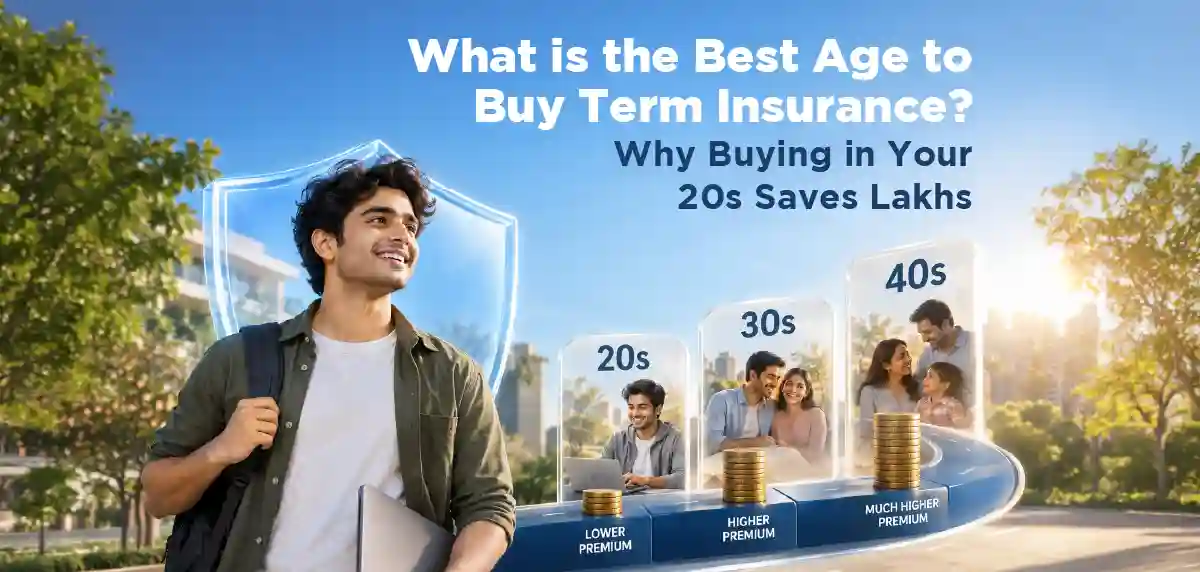
One of the most significant features of term insurance is its affordability. Compared to other forms of life insurance, term insurance policies have much lower premiums, especially for young and healthy individuals. Since the policy only provides death benefits without any maturity benefits or cash value, insurers can offer coverage at a lower cost.
For example, a 30-year-old non-smoker can obtain a high sum assured with relatively low premiums. The earlier you invest in a term insurance plan, the lower your premiums will be.
High Sum Assured
A key feature of a term insurance plan is the high sum assured it offers at a low premium. This ensures your family has sufficient financial support to meet their needs in your absence. When choosing a term insurance policy, make sure to calculate the sum assured based on your family’s current lifestyle, outstanding debts, future expenses such as education or marriage, and inflation.
Using a term insurance calculator can help you determine the appropriate coverage amount for your family’s financial security.
Flexibility in Policy Term
Most term insurance plans offer flexibility in choosing the policy term. You can select the duration of coverage based on your financial responsibilities. For instance, if your children are young and dependent on your income, you may want to choose a longer-term policy. On the other hand, if you expect to retire soon and have fewer financial responsibilities, a shorter policy term may suffice.
Death Benefit Payout Options
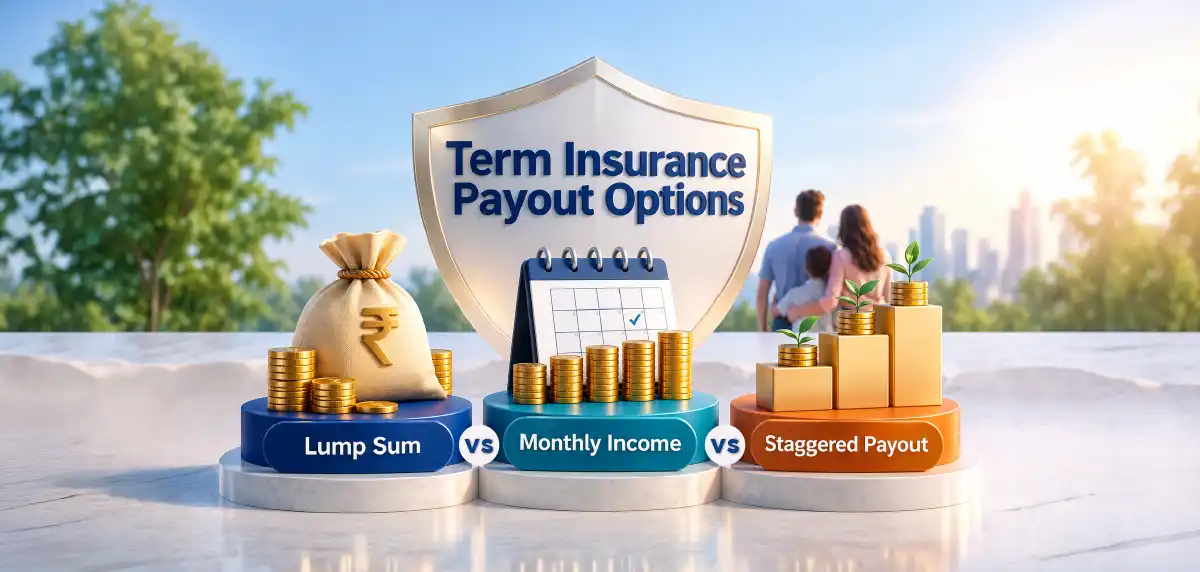
Many term insurance plans now offer flexible payout options for the death benefit. While the traditional lump-sum payout is the most common, some policies provide alternatives such as:
These options can be helpful in managing large sums of money responsibly, especially if your family may not be accustomed to handling significant financial assets.
Lump Sum plus Monthly Income:
A portion of the sum assured is paid immediately, while the rest is distributed as monthly payments over a specified period.
Monthly Income:
The entire sum assured is distributed as monthly income over a pre-defined period, ensuring your family has a steady stream of funds.
Riders for Enhanced Coverage
Another critical feature of term insurance plans is the availability of riders, which offer additional coverage options to address specific risks. Riders come at an extra premium but can significantly enhance the protection provided by your policy. Some popular riders include:
Accidental Death Benefit Rider: This rider provides an additional payout in case of death due to an accident. It’s a good option for individuals working in high-risk occupations or frequently travelling.
Critical Illness Rider: This rider offers coverage for life-threatening illnesses such as cancer, heart attack, or stroke. Upon diagnosis, a lump sum is paid out, which can help with medical expenses and other financial obligations.
Waiver of Premium Rider: In case the policyholder becomes permanently disabled or critically ill, this rider ensures future premiums are waived while the policy remains in force.
Including riders in your term insurance plan can offer a more comprehensive financial safety net for your family.
Tax Benefits**
One of the key advantages and features of term insurance is the tax benefit it provides. Under Section 80C of the Income Tax Act, premiums paid for term insurance qualify for tax deductions up to ₹1.5 lakh per year. Additionally, the death benefit paid out to your nominee is tax-exempt under Section 10(10D), ensuring your family receives the full sum assured without any tax liabilities.
Increasing and Decreasing Term Insurance
Some term insurance plans offer the flexibility to increase or decrease the sum assured based on your evolving financial responsibilities. This feature is particularly useful for individuals whose financial needs may change over time due to factors such as inflation, increased liabilities, or changing family dynamics.
Claim Settlement Ratio
A high claim settlement ratio is one of the most important features of term insurance plans that you should evaluate when choosing a policy. The claim settlement ratio indicates the percentage of claims settled by the insurer out of the total claims received in a given financial year. A higher ratio reflects the insurer’s reliability in honouring claims, which is crucial for ensuring your family receives the promised benefits.
Grace Period and Policy Lapse
In case of missed premium payments, term insurance policies typically provide a grace period, allowing policyholders extra time to pay without losing coverage. If the premium is not paid within the grace period, the policy may lapse. It’s essential to check the grace period provided under your term life insurance policy to ensure you don’t unintentionally lose coverage.
Using a Term Insurance Calculator
When purchasing a term plan, using a term insurance calculator is essential for determining the right coverage and premium amount. A term insurance calculator takes into account various factors such as age, income, financial obligations, and existing debts to recommend the appropriate sum assured and premium for your specific needs. This can help you get a better idea of how a term plan will fit into your overall financial planning.
Choosing the right term insurance plan requires a thorough understanding of its key features, benefits, and suitability for your family’s financial situation. The features of term insurance plans, make them an essential tool for financial planning. By carefully assessing the above features, you can make an informed decision and select a life insurance policy providing peace of mind and financial security for your family.
** Tax exemptions are as per applicable tax laws from time to time.
Frequently Asked Questions
What features should you check before buying a term insurance plan?
You should consider the coverage amount, policy term, premium payment options, death benefit payout choices, available riders, and flexibility offered by the plan. It is also important to check whether the policy provides additional features suited to your financial needs. For instance, IndiaFirst Life GOLD Term Plan offers Life Cover and Life Cover with Return of Premium options, along with flexible premium payment choices.
How much life cover should you choose in a term insurance plan?
Your cover should broadly reflect your income, outstanding liabilities, family expenses, future financial goals and the needs of your dependants. A higher cover may be appropriate if you have substantial loans or dependants. The IndiaFirst Life GOLD Term Plan offers a minimum Sum Assured of ₹1 crore, with the maximum subject to the insurer's Board Approved Underwriting Policy.
Why is policy tenure an important feature of term insurance?
The policy term should ideally cover the period during which your family depends on your income or significant financial liabilities remain outstanding. A longer tenure can provide protection for an extended period. The IndiaFirst Life GOLD Term Plan provides options for extended coverage, including protection up to age 85 or other eligible maturity ages, depending on the selected option and policy conditions.
What premium payment options should you look for?
A suitable term plan should offer payment flexibility that matches your income pattern and financial commitments. Depending on the policy, you may be able to choose regular, limited or single premium payment options. The IndiaFirst Life GOLD Term Plan provides these choices, with limited premium payment terms of 5, 10, 15 or 20 years.
Should a term insurance plan offer different death benefit payout options?
Yes. Different families may have different financial requirements after the policyholder's death. A lump-sum payout may help meet immediate expenses, while regular income can support ongoing household needs. The IndiaFirst Life GOLD Term Plan allows eligible customers to choose a lump-sum payout, monthly level income for 10 or 20 years, or a combination of lump sum and monthly income.
What is Return of Premium in a term insurance plan?
A Return of Premium option is designed for policyholders who want life protection with a maturity-related benefit, subject to the policy terms. Under the IndiaFirst Life GOLD Term Plan, the Life Cover with Return of Premium option provides the applicable Sum Assured on death during the policy term and a maturity benefit as specified under the policy.
Can a term insurance plan provide coverage for a spouse?
Some term plans offer an option to extend protection to a spouse under the same policy. The IndiaFirst Life GOLD Term Plan provides a Soulmate Benefit that can extend life cover to the spouse without an additional premium, subject to applicable eligibility and policy conditions.
Are additional riders useful when choosing term insurance?
Riders can enhance the base protection by providing additional benefits for specified situations. You should select them based on your financial needs rather than adding every available option. The IndiaFirst Life GOLD Term Plan allows policyholders to enhance protection through comprehensive riders, subject to the applicable terms and conditions.
Does a term insurance plan offer any flexibility after purchase?
Certain plans include features that provide flexibility during the policy term. For example, the IndiaFirst Life GOLD Term Plan offers a Smart Exit Value under its Life Cover option. Subject to specified conditions, eligible policyholders can receive an exit value equal to the total premiums paid, after meeting the applicable policy duration and age requirements.
What other benefits should you consider before selecting a term plan?
Apart from life cover, you can assess health-related services, premium discounts, payout flexibility and additional protection options. The IndiaFirst Life GOLD Term Plan includes Health Management Services, with benefits stated as being worth up to ₹75,000 per year, as well as special discounts for salaried customers and female lives, subject to applicable terms.
Before You Go
Turn your financial responsibilities into the right protection, use a term insurance calculator to estimate the cover your family may need.
Term insurance calculator
Disclaimer
IndiaFirst Life Insurance Company Limited, IRDAI Regn No.143, CIN: U66010MH2008PLC183679, Address: 12th & 13th floor, North Tower, Building 4, Nesco IT Park, Nesco Centre, Western Express Highway, Goregaon (East), Mumbai – 400 063. Toll free No – 18002098700. IndiaFirst Life Insurance Company Limited is only the name of the Life Insurance Company and IndiaFirst Life Guardian of Life Dreams Term Plan (UIN 143N081V01) is only the name of the Life Insurance Product and does not in any way indicate the quality of the contract, its future prospects, or returns. For more details on risk factors and terms and conditions, please read the sales brochure carefully before concluding the sale. Trade logo displayed above belongs to our promoter M/s Bank of Baroda and is used by IndiaFirst Life Insurance Co. Ltd under License.