

 Customers
 Distributor
 Join us as an Advisor
 Employee












 :
 :
 :





Key Takeaways
- Long-term cover can protect you for several decades.
- Policy duration should match your family’s dependency period.
- Premium affordability matters when maintaining extended protection.
Your financial responsibilities may continue for decades. A home loan can extend for 20 years, children may depend on your income until they complete their education, and your spouse may require financial protection beyond your retirement. Insurance that ends too early can leave these responsibilities exposed.
Long-term insurance refers broadly to insurance coverage maintained over an extended period. Depending on the product, the cover may last for several decades, until a specified age, or for your entire lifetime. The expression is not a single standard product category, so you must check whether the policy provides pure protection, savings, investment, or lifelong benefits.
Understanding Long-Term Insurance Plan
A long-term insurance plan is designed to offer coverage over an extended period, typically ranging from 10 years to even lifelong. This contrasts with short-term plans, which have limited durations. Long-term plans often come with the benefit of lower premiums compared to short-term renewals, while also locking in premiums early on.
Here are the key features of a long-term insurance plan you may come across.
Extended Coverage Period:
Coverage may extend over decades, typically up to 99 years of age, ensuring financial protection throughout crucial life stages.
Cost-Effective Premiums:
Based on plan type, early enrolment can lead to affordable, fixed premiums.
Comprehensive Protection:
Options for coverage against critical illnesses, accidents, or permanent disability.
How Does Long-Term Insurance Work?
Under long-term insurance, you select a policy duration and pay the applicable premium according to the chosen payment schedule. If a covered event occurs while the policy is active, the insurer provides the specified benefit, subject to the terms and conditions.
For life cover, you may choose a policy that lasts for 20, 30, or 40 years or extends up to an advanced age. Some products may provide protection until age 85, 99, or 100, depending on their eligibility conditions.
The policy duration and premium-payment duration are not necessarily the same. A long-term policy may allow you to pay premiums throughout the coverage period or complete the payments earlier through a limited-pay option.
Is Long-Term Life Insurance the Same as Term Insurance?
Long-term life insurance is a broad description of life cover that remains active for an extended duration. It may include term insurance, whole life insurance, endowment insurance, or another type of policy offering long-duration protection.
A term plan, however, is a specific form of life insurance. It provides cover for a selected period and pays the applicable death benefit if the life assured dies while the policy is active. Pure term insurance generally does not provide a maturity benefit if you survive the policy term.
Therefore, a 40-year term plan can be considered long-duration cover, but not every long-term life insurance product is term insurance.
What Types of Long-Term Insurance Plans Are Available?
Different long-term insurance plans can serve different purposes.
Pure Protection Term Insurance
Pure term insurance focuses on providing a substantial death benefit for a relatively affordable premium. It may suit you when your primary objective is to replace income and protect dependants.
Term Insurance with Return of Premium
This option provides term cover and returns the applicable premiums if you survive until maturity, subject to policy conditions. It generally has a higher premium than comparable pure protection.
Whole Life Insurance
Whole life insurance is designed to provide protection for your lifetime or up to a specified advanced age. Depending on the product, it may also include savings, maturity, or legacy-related benefits.
Savings-Oriented Life Insurance
Savings or endowment policies combine life cover with structured savings. These long-term plans may provide guaranteed and non-guaranteed benefits according to the product terms.
ULIPs
Unit Linked Insurance Plans (ULIPs) combine life cover with market-linked investment. Part of the premium provides insurance, while the remaining amount is invested in selected funds after applicable charges. Returns depend on market performance.
A Savings-Oriented Plan Built for Guaranteed Long-Term Income
If your priority leans towards the savings-oriented category described above rather than pure protection, it's worth looking at the IndiaFirst Life Guarantee of Life Dreams Plan. It combines a life cover with the option to receive a guaranteed, increasing income over an extended period, rather than a one-time payout on death alone.
Depending on the option you choose, the IndiaFirst Life Guarantee of Life Dreams Plan can start paying income as early as the first policy month or defer it to a later stage, alongside a lump sum maturity benefit at the end of the policy term. This structure can suit long-term goals such as a second income stream, a child's future milestones, or added retirement support, while still keeping a life cover in place throughout.
If a long-duration plan that pairs guaranteed income with life cover fits your goals better than a pure term plan, the IndiaFirst Life Guarantee of Life Dreams Plan is worth comparing alongside the protection-focused options above.
Is Long-Term Insurance an Investment Plan?
Insurance and investment serve different primary purposes. Insurance protects you or your family against specified financial risks, while an investment aims to build wealth.
A savings policy or ULIP may function as a long-term investment plan because it includes an investment or savings component alongside life cover. A pure term plan is not a wealth-creation product because its primary purpose is financial protection.
When comparing insurance with a long-term investment plan, examine the life cover, expected or guaranteed benefits, market risk, liquidity, charges, lock-in conditions, and maturity proceeds. Avoid choosing a product only because it combines two functions. It must meet both your protection requirement and financial goal.
Why Consider a Long-Term Insurance Plan?
Having long-term coverage can help you ensure a sense of security through various phases of life. Here are some of the benefits to consider.
1. Financial Security for Dependents
A long-term insurance plan provides a safety net for your loved ones. In the event of your untimely demise, the payout from a life insurance policy ensures your family can maintain their lifestyle, pay off debts, or fund education and healthcare.
2. Protection Against Critical Illnesses
Many long-term plans come with optional riders for critical illnesses. These add-ons can be a lifesaver, covering medical expenses if you are diagnosed with a severe health condition.
3. Legacy and Estate Planning
Life insurance can also be used as a tool for legacy planning, ensuring your wealth is distributed according to your wishes.
Is ₹50 Lakh Term Insurance Sufficient?
Whether 50 lakh term insurance is sufficient depends on your income, expenses, liabilities, dependants, and future goals. The amount may be adequate for one household but insufficient for another.
Suppose your family requires ₹6 lakh annually for regular expenses. A ₹50 lakh payout would equal slightly more than eight years of those expenses before accounting for inflation, liabilities, education, or emergencies.
When assessing 50 lakh term insurance, consider:
- The number of years your family may need income
- Outstanding home and personal loans
- Future education and marriage costs
- Existing investments and insurance
- Inflation during the policy duration
- Income available to the surviving spouse
Your sum assured should be based on the financial gap your family would face rather than a commonly advertised cover amount.
How Long Should Your Policy Last?
Your long-term policy should ideally continue until your major financial responsibilities reduce and your dependants can manage without your income.
For example, you may select a duration that covers you until:
- Your children become financially independent
- Major liabilities are repaid
- Your retirement corpus is adequately built
- Your spouse has sufficient independent resources
- Your family’s existing assets can replace your income
Some people choose coverage until retirement, while others prefer protection up to age 85, 99, or 100. The longest available duration is not automatically the best. You should balance the need for extended protection against the premium.
Calculate Coverage Using an Online Calculator
Planning your insurance needs begins with evaluating the amount of coverage you require. For example, if you are looking for a term insurance plan with a longer coverage duration, you can get estimates for the premium using an online term insurance calculator. It estimates the ideal coverage amount based on factors such as your age, income, lifestyle expenses, and liabilities.
The process for online calculators is fairly simple. You can input the required details, and it will share estimates based on the same. For better results, it is important to first define your requirements. . The displayed premium is indicative. The final amount may change after medical evaluation, underwriting, and verification of the information provided.
What Should You Check Before Buying?
Before choosing among long-term insurance plans, review:
- Policy term and maximum maturity age
- Premium amount and payment period
- Death and maturity benefits
- Exclusions and waiting conditions
- Lapse, revival, and surrender rules
- Available riders and their costs
- Return of Premium or exit features
- Claim and nominee requirements
You should also check whether the premium remains manageable throughout the payment period. A larger cover or longer term provides limited value if the policy lapses because the premium becomes unaffordable.
Integrating Life Insurance Policy into Financial Planning
Choosing a life insurance policy should align with your broader financial goals. Consider factors such as the age of your dependents, liabilities, and your retirement plans. A long-term insurance plan, especially a comprehensive one, can ensure all aspects of your financial future are secured.
Life insurance policies often come with tax benefits. Premiums paid and the payout received may be exempt from taxes under specific sections of the tax code, making these plans even more attractive.
A long-term insurance plan essential for ensuring financial stability for your loved ones. Whether you opt for a term insurance plan or a whole life policy, understanding your coverage needs and financial goals is crucial. Remember, a well-planned life insurance strategy provides not only protection but also peace of mind.
Before You Go
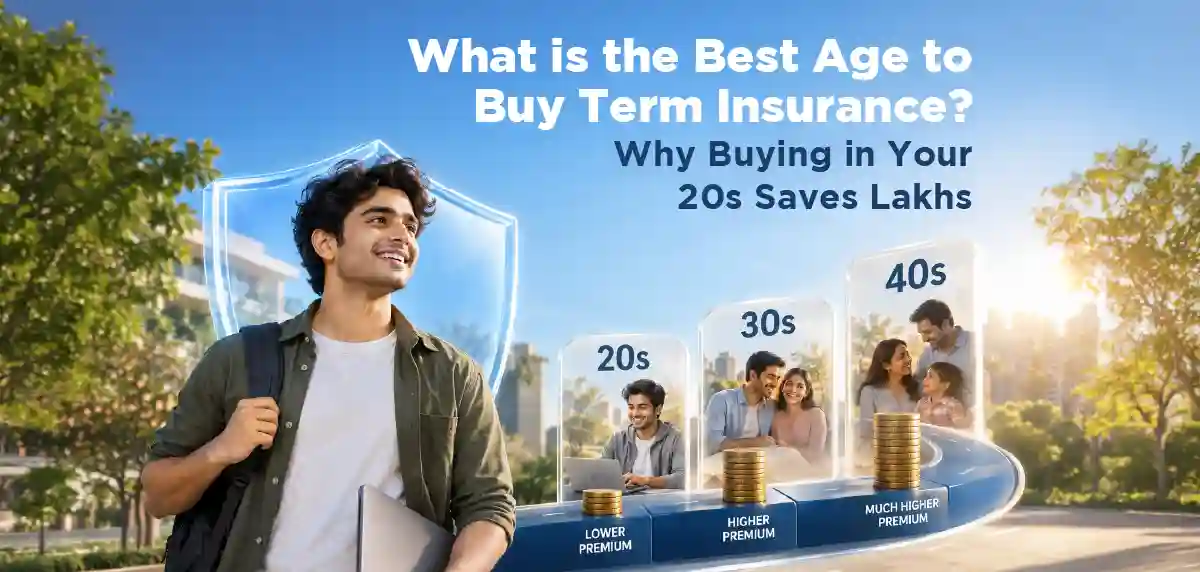
Every year you wait can make life insurance more expensive. The cost of leaving your family financially unprotected could be far greater.
Calculate Your Ideal Life Cover
Disclaimer:
IndiaFirst Life Insurance Company Limited, IRDAI Regn No.143, CIN: U66010MH2008PLC183679, Address: 12th & 13th floor, North Tower, Building 4, Nesco IT Park, Nesco Centre, Western Express Highway, Goregaon (East), Mumbai – 400 063. Toll free No – 18002098700. IndiaFirst Life Insurance Company Limited is only the name of the Life Insurance Company and IndiaFirst Life Guarantee of Life Dreams Plan (UIN 143N080V03) is only the name of the Life Insurance Product and does not in any way indicate the quality of the contract, its future prospects, or returns. For more details on risk factors and terms and conditions, please read the sales brochure carefully before concluding the sale. Trade logo displayed above belongs to our promoter M/s Bank of Baroda and is used by IndiaFirst Life Insurance Co. Ltd under License. Advt. Ref. No.