

 Customers
 Distributor
 Join us as an Advisor
 Employee












 :
 :
 :





Key Takeaways
An insurer may allow an earlier policy commencement date under its product rules.
A lower premium can come with additional premiums and interest payable upfront.
Policy commencement, issue and risk commencement dates can have different contractual purposes.
A birth date can affect the premium quoted for your insurance, but the relevant age is not always the age you celebrated last. Some insurers use your nearest birthday when calculating premiums. An earlier commencement date may place you in a younger pricing category. Before accepting that option, however, you need to compare the savings with the cost of moving the policy date backwards.
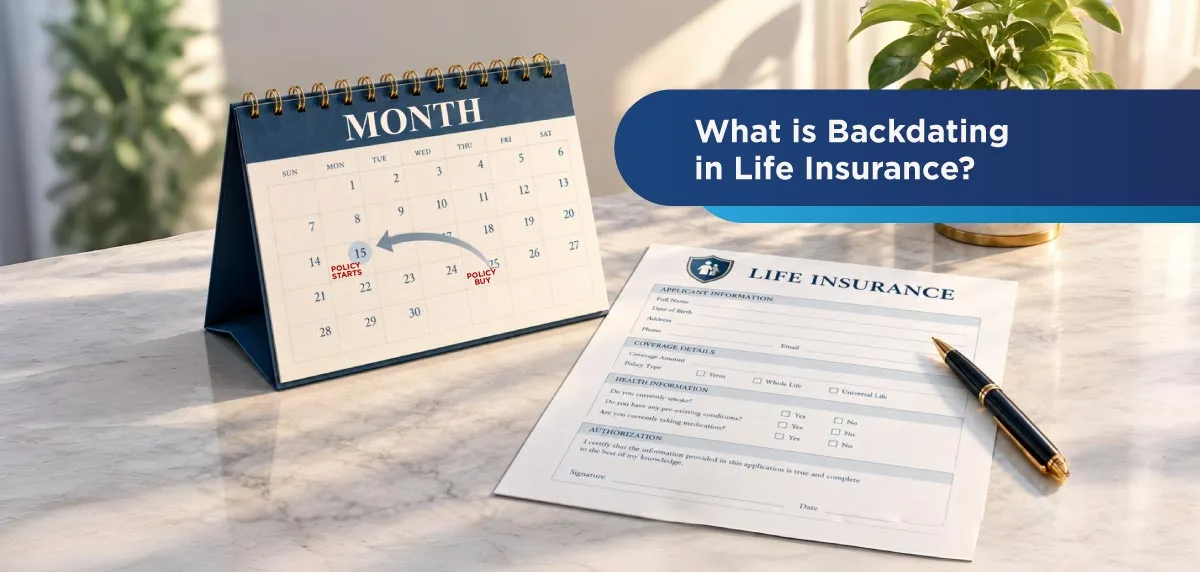
What is Backdating in Life Insurance Policy Terms?
It means an insurer permits a policy commencement date earlier than the actual issuance date, subject to its rules.
The basic life insurance meaning remains unchanged: your policy provides agreed benefits in return for premiums, subject to contractual conditions. The earlier date may affect pricing and payment schedules, but it does not let you rewrite your medical history or invent insurance for an event that has already occurred.
You must request and receive the insurer’s approval. Your health disclosures must remain complete and accurate. Changing dates yourself or providing false information is not an authorised arrangement.
How Can an Earlier Date Reduce Your Premium?
Life insurance backdating can help when an earlier commencement date changes your insurance age. The effect depends on whether the product uses age last birthday, age nearest birthday or another specified basis.
Suppose you are 35 years and seven months old. Under an age-nearest-birthday method, you could be treated as 36. If the insurer permits a date two months earlier, your age then would be 35 years and five months, potentially qualifying for the age-35 rate.
This is an illustration, not a guaranteed discount. Your health, occupation, smoking status, cover amount and selected benefits also influence pricing. Check these details before accepting any revised premium quotation.
How Far Back Can You Move the Date?
The permitted period depends on the insurer and product. Do not assume every policy allows six months, or that a rule mentioned for one insurer applies elsewhere.
When comparing life insurance plans, ask whether backdating is available, the earliest permitted date, and whether financial-year restrictions apply. Some products may not offer the facility at all.
Also ask how the change affects renewal dates, premium payment duration, maturity and the remaining period of cover. An earlier maturity date does not automatically mean a better return.
What Will Backdating Cost You?
Backdating a life insurance policy can require payment of premiums for the earlier period. Interest or other applicable charges may also apply. Request a written comparison showing the total payable under both options.
Consider this hypothetical quotation:
Item | Amount |
Annual premium without backdating | ₹15,000 |
Annual premium with backdating | ₹14,400 |
Annual saving | ₹600 |
Additional upfront cost quoted | ₹2,400 |
Simple break-even period | 4 years |
Here, ₹2,400 divided by ₹600 gives four years. The comparison assumes identical benefits and a continuing annual saving. It ignores the time value of money and any differences in payment dates or coverage duration.
A life insurance calculator can provide an initial estimate. Your insurer must confirm the actual backdated quotation, including all additional payments.
Does Backdating Mean You Were Already Covered?
Do not assume so. The policy commencement date, issue date and date of risk commencement may differ. The contract determines when the insurer accepts the insured risk and how exclusions operate.
Ask for written confirmation of the risk commencement date and the starting point of any waiting period or exclusion. An earlier premium calculation date should not be treated as proof that every benefit applied retrospectively.
Section 45 also uses the latest applicable issuance, risk commencement, revival or rider date for its three-year period. Moving one date backwards does not automatically shorten that statutory period.
How Should You Request It?
If you want to back date a life insurance policy, raise the request during the application process. Provide accurate age proof and complete all medical and financial disclosures.
When buying life insurance online, contact the insurer if the application does not show this option. Before paying, obtain both quotations and confirm the revised dates. You can explore the IndiaFirst Life Guardian of Life Dreams Term Plan for protection needs, while checking directly whether your selected product permits the requested arrangement.
Before You Go
Your family won't remember which plan was cheaper. They'll remember whether the protection was enough when they needed it most.
Calculate Your Ideal Life Cover
Conclusion
Keep the approved quotation and date confirmations with your policy documents. Set renewal reminders using the final schedule, because moving commencement backwards can bring the next payment closer. A premium saving is useful only when you understand the dates and can maintain the cover.