

 Customers
 Distributor
 Join us as an Advisor
 Employee












 :
 :
 :





Key Takeaways
- Healthcare inflation can make future treatment significantly more expensive.
- A longer life increases the risk of exhausting savings.
- A guaranteed lifetime pension can support essential expenses throughout retirement.
Growing old in India brings costs that are easy to underestimate. Regular medicines, diagnostic tests, home assistance, insurance premiums and daily household expenses may continue for decades after your salary stops. The real challenge is not building a corpus. You need a plan that can fund rising healthcare expenses and provide dependable income for a longer lifespan.
What Does Ageing Really Cost in India?
The cost of ageing includes both visible and less obvious expenses. You may budget for groceries, utilities and housing, yet overlook dental care, hearing aids, physiotherapy, mobility equipment, recurring tests or paid caregiving. Even when you own your home, maintenance, property charges and accessibility improvements can affect your monthly budget.
Your spending pattern may also change. Commuting costs could fall, while medical and support expenses may rise.
Why Does Healthcare Inflation Matter?
Healthcare costs do not necessarily rise at the same pace as ordinary household expenses. New treatment methods, hospital charges, specialist fees and long-term disease management can make medical care progressively more expensive. A procedure affordable today may require a much larger amount 15 or 20 years later.
This makes healthcare inflation a critical part of retirement planning. If you estimate future needs using only today’s medical bills, your corpus may fall short. You should separately project routine healthcare expenses, health insurance premiums and a contingency fund for costs not covered by insurance.
Health insurance remains important, but exclusions, consumables and non-hospital care can still require payment from your pocket. Maintain accessible emergency savings alongside your policy.
What is Longevity Risk?
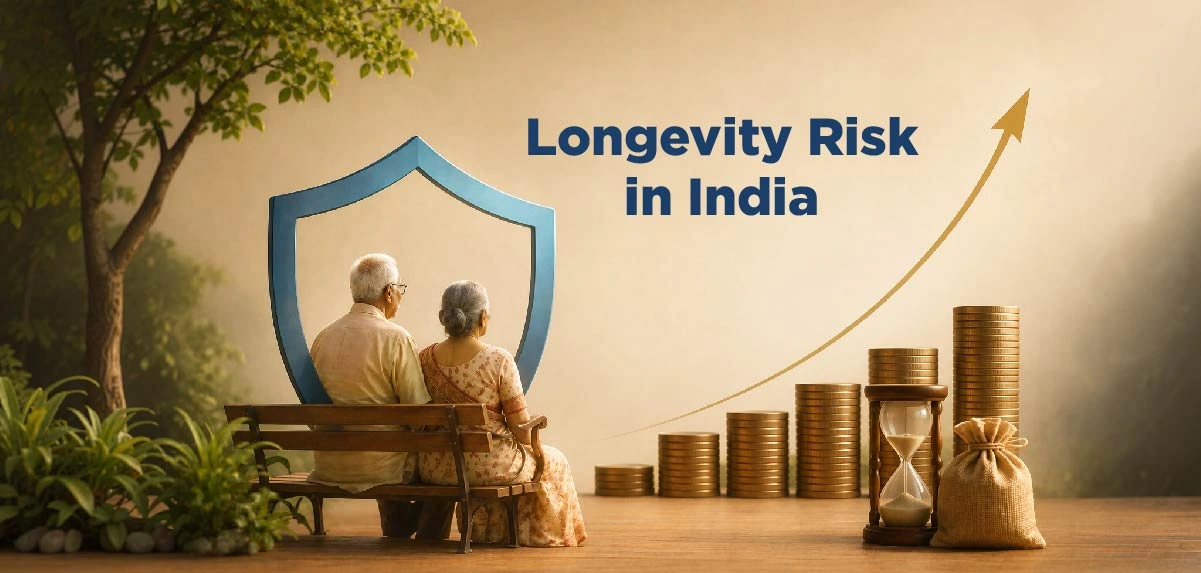
Longevity risk is the possibility that you live longer than the period for which your savings were planned. A long life is welcome, but it creates a difficult financial question. How much can you withdraw each year without exhausting your money?
Suppose you retire at 60 and plan finances until age 80. If you live to 90, the same corpus must support ten additional years of expenses. Higher inflation, weak investment returns or an early medical emergency can widen the shortfall. This is why retirement plans should not be selected only by comparing their expected maturity values.
Why is a Guaranteed Lifetime Pension a Foundational Safety Net?
A guaranteed lifetime pension can create a regular income stream that continues for life, subject to the chosen product’s terms and conditions. This directly addresses longevity risk because the income does not depend on guessing your exact lifespan.
Think of this pension as the foundation of your retirement income, not necessarily the entire structure. You can use it to support essential commitments such as groceries, utility bills, regular medicines and insurance premiums. Investments with market exposure may then be used for growth, discretionary spending or legacy goals according to your risk appetite.
“Guaranteed” generally refers to benefits specified under the policy. Compare whether an option pays for your lifetime, continues for your spouse or returns the purchase price after death.
How Can You Build a Practical Retirement Strategy?
Begin by estimating essential monthly expenses at retirement. Separate healthcare, lifestyle spending and one-time goals so that medical needs are not hidden inside a broad household estimate. Account for inflation and your expected retirement duration.
Next, list predictable income from pensions, rent or other reliable sources. The difference between essential expenses and dependable income is the gap your savings must cover. A retirement planning calculator can help you estimate the corpus required by considering your present savings, years remaining, expected expenses and assumed inflation.
Use a layered approach. Maintain health insurance for large eligible hospital costs, an emergency reserve for immediate payments and suitable investments for long-term growth. Add guaranteed lifetime pension income to cover at least part of your non-negotiable monthly expenses. This reduces the pressure to sell market-linked assets during a downturn.
Review the plan annually and after retirement, a new diagnosis or loss of employer health cover. Your assumptions should evolve with your circumstances.
An IndiaFirst Life Radiance Smart Invest Plan can complement this layered approach by providing an opportunity to participate in market-linked growth while the guaranteed income component is used to address essential retirement expenses. The suitability of such a plan depends on the policy terms, investment horizon and your tolerance for market fluctuations.
Before You Go
You have planned your career. Have you planned the 25 years after it? Estimate the income you may need to protect your independence throughout retirement.
See My Retirement Income
Conclusion
The retirement risk may not be one expense, but the combination of rising medical costs and an unexpectedly long life. Build growth for tomorrow, keep liquidity for emergencies and secure a dependable income floor for essentials. A guaranteed lifetime pension can make that foundation stronger, while periodic reviews help the rest of your strategy keep pace with age and inflation.