

 Customers
 Distributor
 Join us as an Advisor
 Employee












 :
 :
 :





Key Takeaways
- Combine equity and debt funds around specific financial goals.
- Automate transfers and rebalancing instead of timing market movements.
- Check tax conditions before treating internal switches as tax-free.
Diversification inside a ULIP is not simply about selecting several fund names. It means deciding how much of your premium should face market volatility, how much should provide stability, and how that mix should change as your goal approaches. A well-structured ULIP plan can let you make these adjustments within one policy while continuing the life cover, subject to its terms.
When diversifying investment portfolio allocations for a long-term goal, begin with its due date rather than recent fund performance. Consider the time available, the loss you can tolerate, and the amount you need.
What Does Diversification Mean in a ULIP?
A ULIP combines life insurance with market-linked investment funds. Depending on the policy, you may select equity, debt, balanced, or liquid funds. Knowing what ULIP plan is appropriate requires you to compare its fund range, strategies, switching rules, charges, lock-in period, and insurance cover.
Equity funds may offer higher long-term growth potential but can fluctuate sharply. Debt and liquid funds generally aim for greater stability, while balanced funds combine asset classes. Spreading money across them can reduce concentration but cannot eliminate risk.
How Can You Build an Appropriate Fund Mix?
The answer to how to diversify portfolio holdings starts with your risk capacity and time horizon. A distant goal may support greater equity exposure. As the spending date approaches, shifting value towards debt or liquid funds may soften the effect of an equity decline.
Review your allocation annually and after major life changes. A ULIP calculator can estimate a possible maturity value from your premium, tenure, and assumed return. It cannot predict performance, so treat the result as a planning estimate.
How Does Automated Fund Switching Work?
Some ULIPs offer rule-based strategies that transfer units automatically. A trigger strategy may move gains from equity to debt after a threshold. Age-based strategies may reduce equity gradually, while smart-switch strategies may use liquid funds near maturity. Defined-allocation strategies can periodically restore selected fund weights.
Automation can help you diversify your investments consistently and limit emotional decisions. Check the funds involved, transfer timing, opt-out rules, limits, and charges.
What Is an STP in a ULIP?
In mutual funds, an STP moves a fixed amount between schemes at set intervals. A similar ULIP feature may be called a fund transfer strategy, gradually shifting money from debt or liquid funds into equity.
This staggered entry can reduce one-time market exposure. To diversify investments with ULIP this way, confirm the frequency, source and destination funds, transfer period, and charges.
How Does Dynamic Equity-Debt Rebalancing Help?
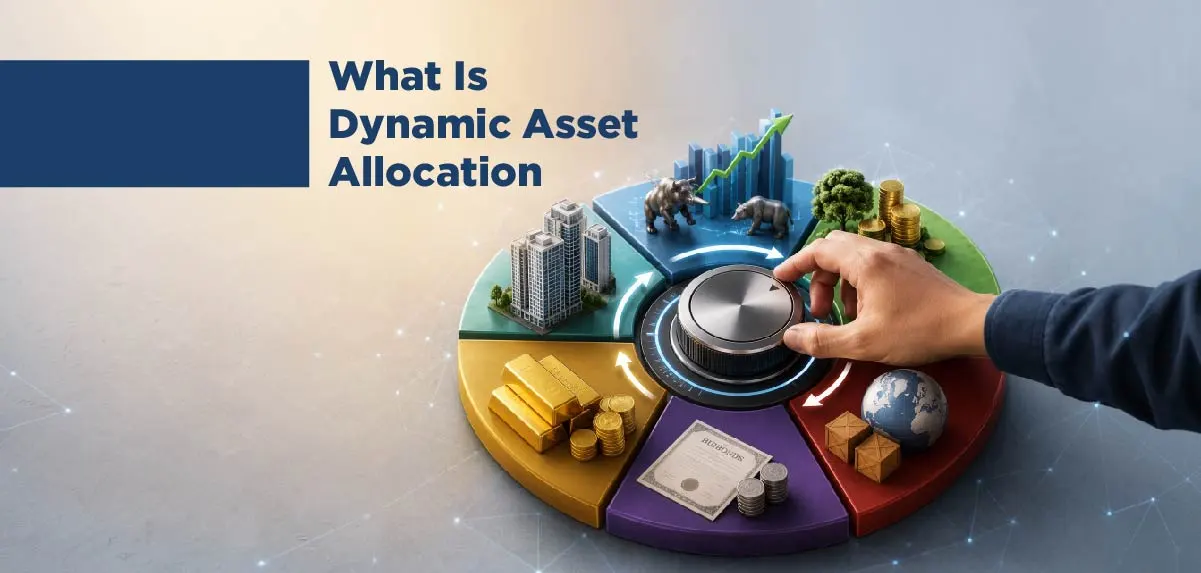
Market movements can distort your intended mix. Dynamic rebalancing restores chosen proportions periodically or changes them through predefined rules. Some ULIPs rebalance on scheduled dates; others alter exposure according to age or time remaining.
When learning how to diversify your portfolio, separate rebalancing from market timing. Rebalancing follows a risk framework; market timing predicts short-term moves. A disciplined rule can control concentration, not prevent every loss.
Are ULIP Fund Switches Tax-Free?
Moving units between funds within the same policy generally does not create an immediate capital-gains tax event. This can make internal allocation more tax-efficient than selling and repurchasing certain investments outside the policy. However, describing every ULIP outcome as tax-free would be inaccurate.
Maturity proceeds may qualify for exemption under Section 10(10D), subject to conditions. For ULIPs issued on or after 1 February 2021, the aggregate annual premium threshold is generally ₹2.5 lakh, together with the applicable premium-to-sum-assured condition. If the requirements are not met, gains may be taxable. Amounts received on death are treated separately under the rules.
What Should You Check Before Choosing a Strategy?
Compare available funds, risk levels, charges, switching provisions, premium redirection, and automatic strategies. Check how the five-year lock-in affects access to money. Choose a method you can follow through different market cycles; frequent discretionary switching can turn diversification into speculation.
Also confirm whether changing strategies affects future premium allocation or only the units accumulated in the policy.
If you are comparing ULIP investment plans, review the fund choices, switching flexibility, charges, life cover, and other policy terms before making a decision. For example, the IndiaFirst Money Balance Plan can be considered alongside other ULIP options based on your investment requirements and preferred allocation approach.
Before You Go
Saving tax can help you keep more of your money. Investing wisely can help that money grow for your future goals.
Calculate Your Potential ULIP Returns
Conclusion
Record your selected allocation, review date, and automatic-switch rules in one place. This investment note can stop a temporary market fall from becoming an impulsive strategy change. It also gives you a benchmark for future reviews. Before acting, confirm that your policy supports each feature, applies it to the intended funds, and keeps the costs acceptable.