

 Customers
 Distributor
 Join us as an Advisor
 Employee












 :
 :
 :






Key Takeaways
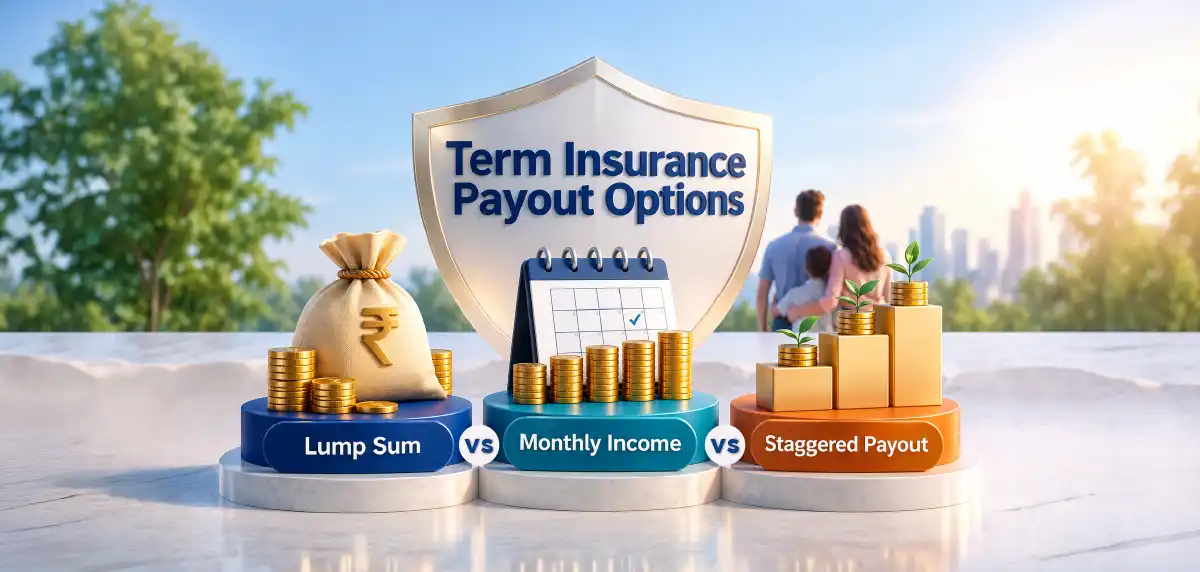
- Lump sums address debts and other immediate financial commitments.
- Monthly income supports recurring expenses through scheduled instalments.
- Staggered payouts combine immediate liquidity with continuing income support.
Choosing ₹1 crore of cover answers how much protection your family receives, not how the money reaches them. A home loan may require immediate settlement, while rent, school fees, and parents’ care continue monthly. The right term insurance payout turns a headline sum assured into a practical family cash-flow plan.
Make the decision before the policy begins. Available choices, income periods, instalment rules, and flexibility vary by product.
What Does a Term Insurance Payout Mean?
The term insurance meaning begins with fixed-period protection. If the life assured dies during that period and the claim is accepted, the insurer pays the death benefit according to policy terms.
Knowing what life insurance is helps separate cover from payout. The sum assured is the protection amount; the payout mode determines whether it is released at once or over time. A life insurance policy payout can follow different schedules for the same sum assured.
What Are the Main Payout Options?
The common types of term insurance payouts are lump sum, monthly income, and a staggered combination. Products may specify percentages and income periods, so check the available choices before purchase.
These differ from the types of term insurance, such as level, increasing, decreasing, or return-of-premium plans. One concerns protection; the other concerns benefit distribution.
How Does the Lump Sum Option Work?
Under this option, the full death benefit is paid after claim approval. This insurance payout can help your nominee clear debts, meet urgent costs, or create an investment corpus.
It offers immediate access and flexibility. However, poor investment decisions, fraud, pressure, or rapid spending can shorten how long the money lasts. It may suit experienced nominees or families with large immediate liabilities.
How Does the Monthly Income Option Work?
Monthly income divides the benefit into scheduled instalments for a stated period. It can replace part of your salary and support recurring expenses without requiring immediate management of the entire amount.
A monthly term life insurance payout supports budgeting but provides less immediate liquidity. Inflation may reduce a fixed instalment’s purchasing power. Check the start date, duration, whether income increases, and what happens if the nominee dies during the payout period.
How Does a Staggered or Combination Payout Work?
A staggered structure pays one portion immediately and distributes the balance monthly. The lump sum can settle debts, while instalments support daily living, balancing liquidity with discipline.
Certain term life insurance products offered by IndiaFirst Life Insurance allow 50% as a lump sum and 50% as monthly income for a selected period. Ratios and durations vary, and the split may require selection at inception.
The IndiaFirst Life Guardian of Life Dreams Term Plan provides a combination payout option, allowing the nominee to receive a portion as a lump sum and the remaining amount as monthly income, based on the option selected at policy inception and applicable policy terms.
How Do the Three Options Compare?
Factor | Lump sum | Monthly income | Staggered payout |
Immediate liquidity | High | Limited | Moderate to high |
Regular income | Must be created by nominee | Built into payout schedule | Available on remaining portion |
Useful for | Debts and major goals | Household expenses | Debts plus ongoing expenses |
Main concern | Managing a large amount | Inflation and limited upfront cash | Choosing an appropriate split |
No option is universally superior. The best life insurance payout depends on liabilities, financial knowledge, the income gap, and money-management ability.
How Should You Choose the Right Payout?
Separate immediate from recurring needs. List loans, education commitments, and emergency costs first. Then calculate household bills, healthcare, parental support, savings, spouse income, and employer benefits.
Use a term insurance calculator to estimate cover before selecting the payout mode. Instalments cannot correct an inadequate sum assured, while large cover may still fail if upfront liquidity is insufficient.
Discuss the choice with your nominee. The selected term insurance payouts should reflect their financial confidence, inflation, and the expected dependency period.
What Should You Check in the Policy?
Before purchasing life insurance, check availability, selection timing, permitted splits, income periods, payment frequency, and claim conditions. Confirm whether the nominee can change the choice or instalments can pass to a successor.
Read the policy wording carefully because illustrations cannot replace contractual payout rules.
Before You Go
Your family won’t remember which plan was cheaper. They’ll remember whether the protection was enough when they needed it most.
Calculate Your Ideal Life Cover
Conclusion
Create a beneficiary cash-flow note before selecting the payout. Record debts requiring immediate payment, essential monthly costs, available savings, and who can manage investments. This gives your nominee a financial map alongside the policy documents if a claim becomes necessary.