

 Customers
 Distributor
 Join us as an Advisor
 Employee












 :
 :
 :






Key Takeaways
- Buying early can help you lock in lower premiums.
- Your health and lifestyle influence underwriting and pricing.
- A long policy term can protect future financial responsibilities.
Why Your Age Matters When Buying Term Insurance
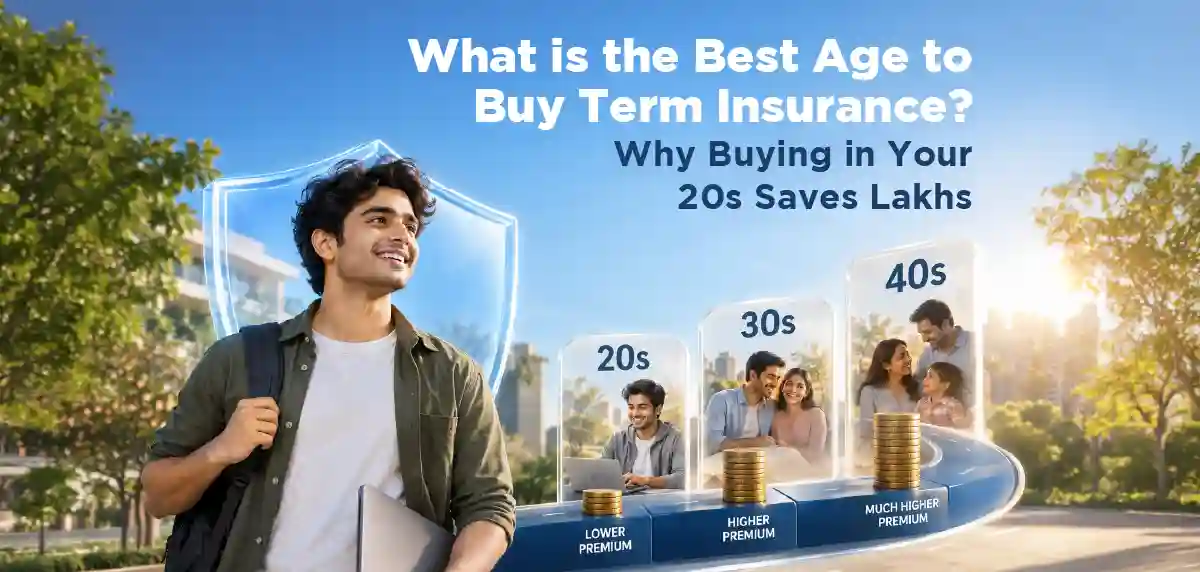
The best time to buy term insurance is usually before your financial responsibilities become substantial. When you are young, you may not yet have a home loan, children or dependent parents. However, this is also when you can potentially secure financial protection at a lower cost.
Your age affects the insurer’s assessment of mortality risk. As you grow older, the likelihood of health conditions and other risk factors generally increases. Insurers account for this while calculating premiums. This means delaying your purchase may make the same cover more expensive, even if your income and lifestyle remain unchanged.
Understanding the life insurance meaning is important here. Life insurance is designed to provide financial support to your family if you die during the policy term. A term plan offers this protection for a fixed period, usually without an investment or maturity benefit.
What is the Best Age to Get Life Insurance?
There is no single age that works for everyone. The right decision depends on your income, dependants, health, liabilities and long-term financial plans. However, many people may find their 20s or early 30s suitable because they can obtain a longer policy term at a relatively lower premium.
If you have started earning and someone depends on your income, you may already have a reason to consider a life insurance policy. You may also want to buy cover if you have taken a loan, started supporting your parents or expect to marry and raise a family in the future.
So, what age should you get life insurance? You do not necessarily need to wait until marriage or parenthood. If your income supports another person or you have outstanding debt, buying earlier can help create a financial safety net.
How Buying in Your 20s Can Save Lakhs
Consider a healthy non-smoking applicant seeking ₹1 crore term cover until age 60. The actual premium will vary by insurer, policy term, occupation, medical history and other factors. The following is only an illustrative comparison.
Entry age | Illustrative annual premium | Approximate payment period | Total premiums paid |
20 years | ₹8,000 | 40 years | ₹3.2 lakh |
30 years | ₹11,500 | 30 years | ₹3.45 lakh |
40 years | ₹20,000 | 20 years | ₹4 lakh |
These figures are not quotations. They demonstrate how the annual premium may rise as you age. In this example, buying at 20 instead of 40 could reduce the total premium outgo by approximately ₹80,000. For higher cover amounts, longer terms or different underwriting profiles, the difference can run into several lakhs.
Savings don't come only from paying for more years. A younger applicant may receive a lower annual rate because the insurer expects a lower mortality risk during the initial years of the policy. Locking in that rate early can be useful, particularly if your health changes later.
The Advantage of Lower Mortality Costs
Mortality cost refers to the cost associated with the risk of the insured person dying during the policy term. It is one of the factors used in pricing protection-oriented insurance products.
When you are younger, your mortality risk is generally lower. As a result, your insurer may charge less for the same sum assured compared with an older applicant. This is one of the main reasons the best age to get life insurance is often considered to be as early as your earning years.
Buying young may also reduce the possibility of exclusions, premium loading or application delays caused by newly developed health conditions. However, you should always disclose your medical history honestly. A lower premium is useful only when the policy remains valid, and the claim can be assessed correctly.
What is the Age Limit in Life Insurance?
The age limit in life insurance depends on the insurer and the specific product. Some term plans may allow entry during the early working years, while others accept applications from older individuals. The maximum entry age may also differ from the maximum age until which the cover continues.
For example, an insurer may permit entry at an older age but offer a shorter policy term. If you buy at 45, you may not receive the same duration available to someone who purchases at 25. A shorter term can also leave gaps in protection if your financial responsibilities continue beyond the policy expiry date.
Before buying, check the minimum and maximum entry age, maximum maturity age, available policy terms, premium payment options and medical assessment requirements.
Is Term Insurance Useful If You Are Single?
You may still need term insurance if you are single. Your parents, siblings or another family member may depend on your income. You may also have education financing, a personal loan or other liabilities that could become a burden for your family.
Even if nobody currently depends on you, buying early may help you obtain cover while you are healthy. Later, when you have dependants, you may be able to increase protection through an additional policy, subject to eligibility and underwriting.
If you are looking for dedicated term protection, the IndiaFirst Life Guardian of Life Dreams Term Plan can also be considered while evaluating your long-term life cover needs.
How to Choose the Right Age and Cover
Do not select a policy only because its premium is low. Estimate your income replacement needs, outstanding debts, future goals, education costs and inflation. You should also account for existing savings and other insurance coverage amounts. Review the policy wording, claim conditions, exclusions, riders and insurer’s service record before making a decision.
Once you have estimated your needs, you can explore IndiaFirst Life term insurance plans and compare the available cover amounts, policy terms and premium payment options. Check the selected plan’s entry-age limits and eligibility conditions, and choose a cover duration that accounts for how long your family may depend on your income.
Before You Go
Your premium is cheaper today than it will be tomorrow. Every year you wait can make life insurance more expensive. Calculate the cover your family may need before choosing a life insurance policy.
Lock In My Premium
Conclusion
The right age to buy term insurance is when you have an income, financial responsibilities or people who would be affected by your absence. For many people, that point arrives in their 20s. Starting early can help you access lower mortality-based pricing, choose a longer term and potentially save lakhs over the policy duration. The most important step is to buy adequate cover while you are healthy, disclose all relevant information and keep the policy active throughout the term.
You can explore IndiaFirst Life term insurance plans when assessing your protection needs. Compare the selected plan’s eligibility criteria, cover options and policy duration against your responsibilities, and choose a premium payment commitment you can sustain over time.
Disclaimer
IndiaFirst Life Insurance Company Limited, IRDAI Regn No.143, CIN: U66010MH2008PLC183679, Address: 12th & 13th floor, North Tower, Building 4, Nesco IT Park, Nesco Centre, Western Express Highway, Goregaon (East), Mumbai – 400 063. Toll free No – 18002098
Company and IndiaFirst Life Guardian of Life Dreams Term Plan (UIN 143N081V01) is only the name of the Life Insurance Product and does not in any way indicate the quality of the contract, its future prospects, or returns. For more details on risk factors and terms and conditions, please read the sales brochure carefully before concluding the sale. Trade logo displayed above belongs to our promoter M/s Bank of Baroda and is used by IndiaFirst Life Insurance Co. Ltd under License.