

 Customers
 Distributor
 Join us as an Advisor
 Employee












 :
 :
 :





Key Takeaways
Buy cover according to responsibilities, including support for parents.
Starting a ULIP early gives your investments more time for potential compounding, subject to market risks and charges.
Review your policy when income, dependants or outstanding loans change.
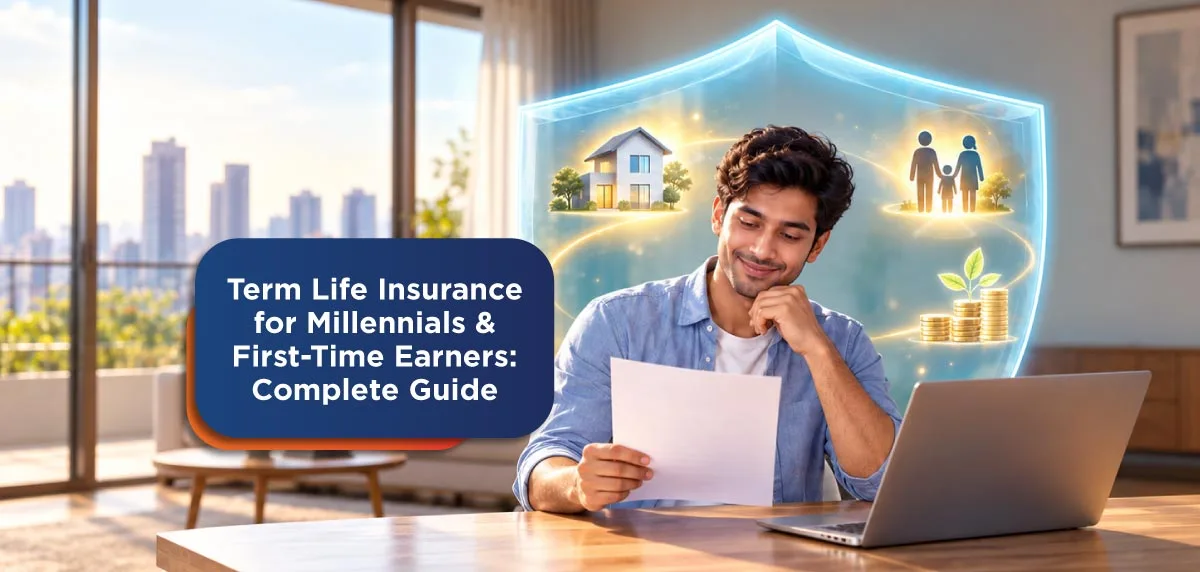
Your first salary may start paying someone else’s electricity bill before it pays for your own holiday. That contribution creates a financial responsibility, even if you are unmarried. For millennials managing children, ageing parents or a mortgage, the same question carries greater weight: how would these expenses be met without your income?
Understanding term insurance for first-time earners in India helps you turn that question into a practical protection plan.
What is Life Insurance and How Does Term Cover Work?
If you are wondering what is life insurance, it is a contract under which an insurer provides benefits linked to the insured person’s life, in exchange for premiums, subject to policy terms.
The term insurance focuses on protection for a chosen period. If you die during that period while covered, the insurer pays the eligible death benefit. A standard pure term policy generally pays no maturity benefit if you survive the term. Return of premium variants have different benefits and pricing.
This cover can support your family’s finances after your death. It does not replace health insurance for hospital expenses or savings for retirement.
Do You Need Cover With Your First Salary?
Start with who depends on your earnings. Parents receiving monthly support, a spouse sharing household costs or a co-borrower relying on you for repayments can make life insurance relevant immediately.
If nobody depends on you financially and you have no liabilities affecting others, your immediate protection needs may be smaller. Build emergency savings and assess health cover alongside your longer-term insurance requirements.
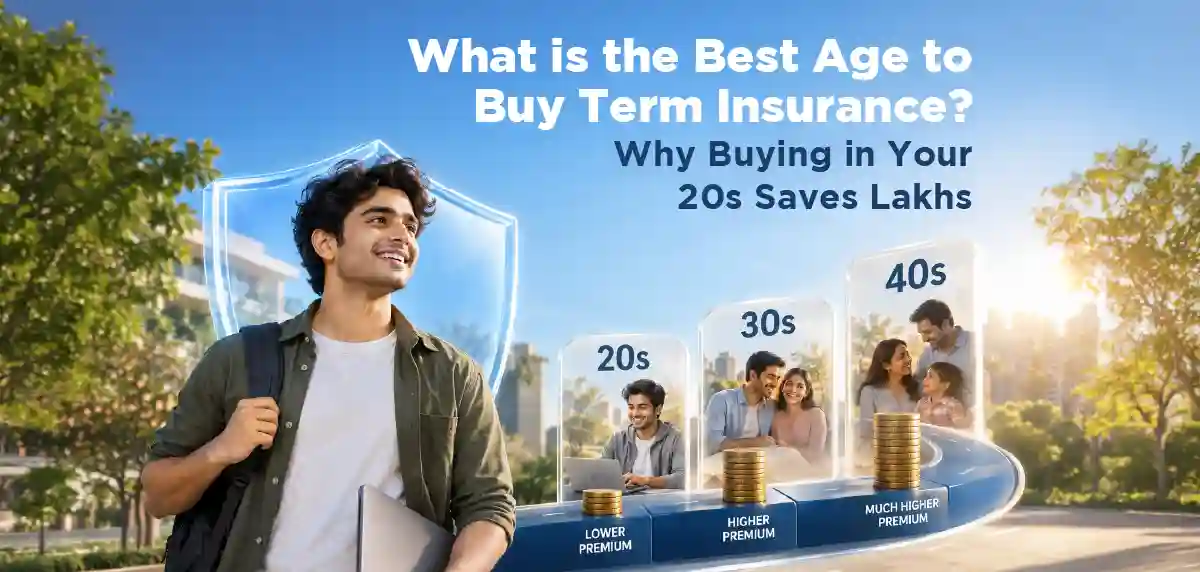
Buying younger can mean lower premiums for comparable cover, but health, tobacco use, occupation and underwriting also influence the offer. Your employer’s cover may end when employment ends; check its conditions before relying on it.
How Can Starting a ULIP Early Support Long-Term Goals?
Once you have assessed protection and emergency needs, consider how to fund goals such as retirement. A Unit Linked Insurance Plan, or ULIP, combines life cover with market-linked investments.
Starting early gives invested money more time for potential compounding- returns that remain invested can themselves generate further returns. Beginning at 25 rather than 35 gives you ten additional years before a retirement goal at 60. Consistent contributions also increase the amount invested.
However, ULIP returns are not guaranteed. Market performance, fund selection and charges, including mortality and fund management charges, affect your eventual corpus. ULIPs have a five-year lock-in, making them unsuitable for emergency savings. i
You can explore the IndiaFirst Life Radiance Smart Invest Plan for its life cover and investment options. Review the benefit illustration, charges and investment horizon before deciding. Its insurance component should also be assessed against your overall protection requirement.
How Can You Compare Plans Sensibly?
The best life insurance for millennials depends on responsibilities, affordability and policy terms. Compare these features before deciding:
Coverage period: Match protection to the years your dependants need support and major debts remain outstanding.
Premium commitment: Distinguish the coverage period from the premium payment period. Shorter payment schedules can require larger instalments.
Benefits and exclusions: Read payout conditions, exclusions and rider definitions. Add optional protection only when it addresses a specific need.
Claims support: Check documentation requirements, service channels and published claims information alongside the policy wording.
The life insurance millennials choose should also remain affordable through job changes and other commitments. Calculate the annual outgo, including selected riders, before signing up.
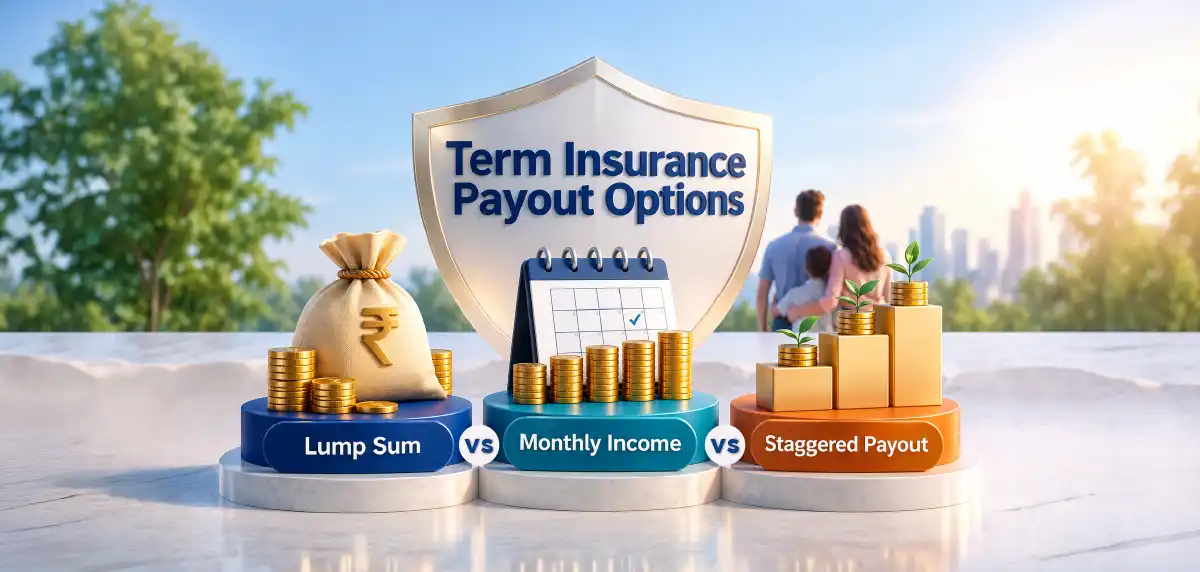
You can explore the IndiaFirst Life Guardian of Life Dreams Term Plan, which offers Life Cover and Life Cover with Return of Premium options, with different death benefit payout choices. Compare the option’s terms and costs against your needs; availability is subject to eligibility and underwriting.
What Should You Check Before Buying?
Complete the proposal accurately. Disclose medical history, tobacco use, occupation, income and existing insurance as requested. Review answers yourself, even when someone helps with the application.
For term insurance for first-time earners in India, income documentation and the insurer’s financial assessment can affect available cover. An advertised amount is not automatic eligibility.
Record your nominee correctly, share policy access details with them and set premium reminders. After issuance, check the policy schedule against the cover, payment period and benefits you selected.
Before You Go
The day you’re not there, your family’s rent won’t stop. School fees won’t stop. Monthly bills won’t stop.
Make sure their life can continue even when yours cannot.
Check Your Monthly Premium
Conclusion
Set a review date when you organise your salary or budget. A pay rise alone may not require more cover, but a new dependant or shared loan can change the calculation. Keep your life insurance aligned with those responsibilities, and ensure your family knows how to use the protection you have arranged.