

 Customers
 Distributor
 Join us as an Advisor
 Employee












 :
 :
 :





Key Takeaways
Section 45 limits when your insurer can challenge a life insurance policy.
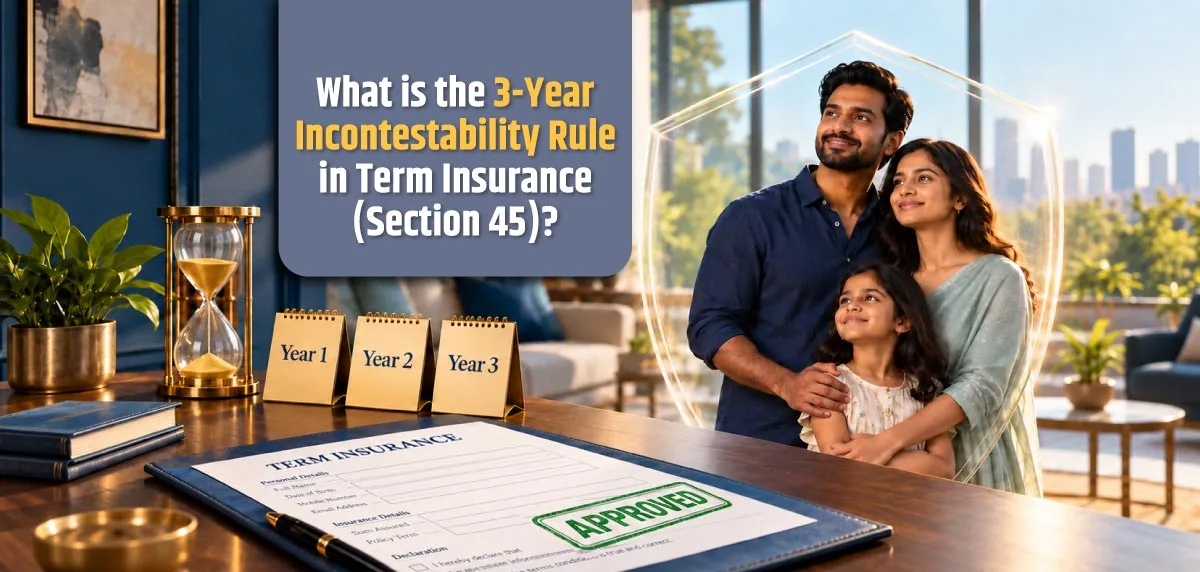
Three years run from the latest applicable issuance, risk commencement, revival or rider date.
Honest disclosures and uninterrupted premiums remain essential for protecting your family.
An old medical prescription can become unexpectedly important when your family files an insurance claim. If your application omitted a health condition, can your insurer question the policy indefinitely? Section 45 of the Insurance Act, 1938 sets a legal boundary. Understanding the 3-year rule in term insurance helps you separate your insurer’s right to investigate disclosures from your family’s right to receive a valid policy benefit.
What Does Section 45 Actually Say?
After the applicable three years expire, your life insurance policy cannot be called into question on any ground whatsoever. This protection includes challenges based on fraud or incorrect disclosures. During those three years, however, an insurer can question the policy on grounds permitted by Section 45.
When Does the Three-Year Period Begin?
You must identify the latest of four dates:
The date your policy was issued.
The date your insurance risk cover commenced.
The date your policy was revived.
The date of a rider to your policy.
Suppose your policy was issued on 1 January 2026, but risk cover began on 10 January 2026. Assuming no subsequent revival or rider, you count three years from 10 January.
Reviving a lapsed policy later can restart this calculation. Therefore, the 3-year rule in term insurance does not always run from your original purchase date. Keep revival confirmations and rider documents alongside your policy schedule.
Can Your Insurer Reject a Claim Within Three Years?
A claim arising during this period is not automatically rejected. Your insurer needs legally valid grounds to challenge the policy.
Fraud involves intentional deception, such as deliberately concealing a known medical condition. Section 45 also permits challenges involving incorrect statements or suppression of facts material to life expectancy, even without fraud.
For a nonfraudulent challenge, the insurer must establish that the fact directly affected its risk and that it would not have issued the policy had it known the truth. An insignificant error is not automatically sufficient.
The insurer must communicate its grounds and supporting materials in writing. If repudiation concerns material misstatement or suppression without fraud, premiums collected must be refunded within 90 days of repudiation.
You can contest allegations of fraud with evidence that your answers reflected your knowledge and belief, without deliberate concealment, under the safeguards in Section 45.
Does Completing Three Years Guarantee Every Payout?
No. Incontestability does not revive expired cover or create benefits your contract never provided. Your insurer can still verify that the insured event occurred, check claim documents and apply valid policy terms.
For example, if your cover has ended because of unpaid premiums, merely reaching the third anniversary does not restore it. Similarly, a rider pays only for events covered by that rider.
Section 45 also allows an insurer, where entitled, to request proof of age and adjust policy terms if your age was incorrectly stated. Such an adjustment does not itself amount to contesting the policy.
Is This a Three-Year Waiting Period?
No. The 3-year rule in term insurance concerns contestability, not a blanket postponement of death benefits. A valid claim can be payable before three years, subject to coverage and policy conditions.
When comparing term insurance plans, check actual waiting periods and exclusions separately. Do not assume your family must wait three years before receiving protection.
How Can You Reduce Avoidable Claim Disputes?
Answer proposal questions accurately, including those about medical history, tobacco use, occupation and existing insurance. Review every answer yourself, even when someone else completes the form. Keep written acknowledgements of corrections.
Choose term insurance plans around your dependants’ expenses, liabilities and future needs. For instance, the IndiaFirst Life GOLD Term Insurance Plan offers a choice of Pure Protection or Return of Premium, the IndiaFirst Life Super Protection Plan offers flexibility to pay premiums, lets you choose the policy duration and sum assured. If you are considering 1 crore term insurance, assess whether ₹1 crore would actually meet those responsibilities.
A term plan calculator can help estimate premiums, but it cannot confirm underwriting acceptance or guarantee claim approval. Keep premiums current and explain the claim process to your nominee.
Before You Go
One day, your term insurance may become your family's financial lifeline. Make sure it's enough.
Calculate Your Ideal Life Cover
Conclusion
Create a simple policy timeline for your nominee, recording issuance, risk commencement, revival and rider dates. This gives your family something practical to consult if a claim is questioned. Knowing which date controls the three-year calculation can be more useful than remembering the purchase anniversary alone.