

 Customers
 Distributor
 Join us as an Advisor
 Employee












 :
 :
 :





Key Takeaways
- Credit-linked cover can help settle outstanding debt after death.
- Choose level or reducing protection based on the liability.
- Compare scope, tenure, exclusions, beneficiaries, and payout arrangements.
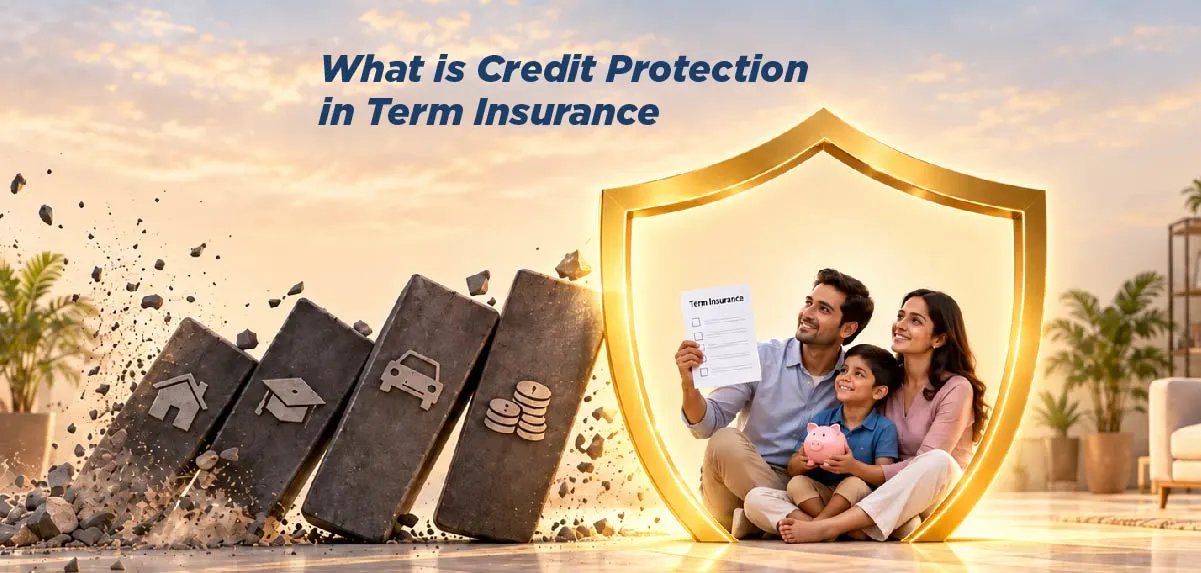
A long-term loan depends on years of future income. If that income stops because of your death, your family may have to use savings, sell an asset, or manage EMIs with less income. Credit protection in term insurance helps reduce this risk by providing money for eligible outstanding debt.
The arrangement may be an individual policy or group credit life cover offered through a lender. These approaches differ in ownership, beneficiaries, payout structure, portability, and family benefits.
What Does Credit Protection Mean?
Credit protection refers to life insurance cover linked directly or indirectly to a financial liability. If the insured borrower dies during the policy term and the claim is accepted, the benefit helps repay the covered loan. Depending on the policy structure, the insurer may pay the lender, your nominee, or both according to the stated arrangement.
Understanding what term insurance is clarifies the difference. A standard policy provides a selected sum assured for a fixed period, which your nominee can use for various needs. Credit-linked cover focuses more narrowly on debt.
How Does Credit Protection Work?
You identify the loan amount and repayment tenure, then select level or reducing cover. You pay the premium, provide accurate personal and medical information, and keep the policy active.
If you die during the covered period, the claimant informs the insurer and submits the required documents. After approval, the benefit settles the loan fully or partly. Any surplus reaches your nominee only when the policy and assignment permit it.
What Are Level and Reducing Credit Covers?
Level cover keeps the sum assured broadly unchanged. It can clear the loan while leaving additional money for your family. An independent term insurance policy commonly follows this structure, subject to plan terms.
Reducing cover follows the scheduled decline in your loan balance. It aligns protection with the debt but may leave little additional benefit after the lender’s dues are cleared.
IndiaFirst Life explains that reducing credit life cover is synchronised with a falling loan balance, while level cover remains constant.
Which Liabilities Can Be Protected?
Credit-linked cover may be available for home, vehicle, education, personal, business, agricultural, or other eligible loans. Availability depends on the insurer, lender, borrower, and underwriting rules.
For a joint loan, confirm whose life is insured, whether joint cover applies, and whether the surviving borrower remains responsible for an uncovered balance.
What Are the Main Features?
The features of term insurance used for liability planning may include a fixed sum assured, chosen policy tenure, death benefit, premium payment options, nomination, and optional riders. Credit-specific plans may additionally provide reducing cover, lender assignment, single-premium payment, or group enrolment.
Some plans cover accidental total permanent disability or specified critical illnesses. Check the covered event, waiting and survival periods, exclusions, benefit amount, and effect on the remaining life cover.
How Much Cover Do You Need?
Begin with the current outstanding principal and add other liabilities. If one policy covers debt and family needs, separately include household expenses, education goals, and income replacement.
A term insurance calculator can estimate overall cover and an indicative premium. Do not match the sum assured only to today’s loan balance when the policy must also protect your family. Check existing policies and employer benefits first.
What Should You Compare Before Buying?
Compare the cover pattern, claim recipient, continuity after refinancing or prepayment, and treatment of a single premium after early closure. Review exclusions, documents, cancellation provisions, medical requirements, and taxes.
Ask for an amortisation or benefit schedule before purchase. Compare it with your loan statement, especially after rate changes, moratoriums, restructuring, or part-prepayments, because the insured schedule and actual outstanding balance may not always move exactly together.
You should also distinguish the lender’s loan account from the insurance contract. Confirm the insured amount, policy term, nominee or assignee details, and claim route in writing. Never assume that paying the loan EMI automatically keeps every insurance benefit active.
If you are comparing term insurance plans, assess the coverage, policy tenure and premium against your financial responsibilities rather than choosing a plan based only on the premium amount.
For those seeking dedicated financial protection, the IndiaFirst Life Guardian of Life Dreams Term Plan can be considered alongside other term insurance options, subject to its policy terms and eligibility criteria.
Before You Go
You've worked hard to build a home for your family. Make sure they can continue living in it, even if you're no longer there to pay the EMI.
Calculate Your Ideal Life Cover
Conclusion
Effective credit protection begins with a clear record of every liability, borrower, insurer, nominee, and outstanding balance. Keep all policy documents easily accessible and tell your nominee how the claim should be initiated. When choosing term insurance, ensure the cover does not merely close a loan account but also preserves the financial plans that the loan was meant to support.