

 Customers
 Distributor
 Join us as an Advisor
 Employee












 :
 :
 :





Key Takeaways
Annuities offer contractual income; SWPs depend on investment performance.
Compare liquidity, inflation exposure, taxation and benefits for your spouse.
Combining both may balance essential expenses with flexible spending.
Your final salary arrives once, but your electricity bill keeps arriving. Retirement therefore changes the question from “How much have I saved?” to “How will these savings pay me?”
UNFPA projects that India will have 346 million people aged over 60 by 2050, nearly 21% of its population. For your household, the practical challenge is funding an uncertain number of years without employment income.
Understanding annuity vs SWP for retirement in India helps you separate dependable income from withdrawals that require ongoing investment management.
How Does Annuity Work?
An annuity is an insurance contract that provides payments according to the option you select. An immediate annuity starts paying after the agreed payment interval; a deferred annuity starts later.
Lifetime options address longevity risk: the possibility that you outlive your savings. However, accessing the purchase amount can be restricted, and death benefits depend on the option chosen.
Your annuity planning should consider whether income must continue for your spouse and whether returning the purchase price to beneficiaries matters.
For example, the IndiaFirst Life Guaranteed Annuity Plan offers immediate and deferred options, alongside joint-life and return-of-purchase-price choices, subject to policy conditions.
How Does an SWP Work?
A systematic withdrawal plan is a facility for redeeming mutual fund units periodically. You choose the withdrawal amount and frequency, subject to scheme rules. sebi.gov.in
The money received can include both invested capital and gains. It is not automatically interest or investment profit.
Suppose you withdraw ₹10,000 monthly. At a net asset value of ₹50, you redeem 200 units. At ₹40, the same withdrawal requires 250 units. Falling markets therefore force you to sell more units, leaving fewer available for a recovery.
This is why annuity vs systematic withdrawal plan comparisons must look beyond the monthly amount credited.
What is the Main Difference?
The central difference between annuity and SWP concerns who bears the risk of sustaining income.
Factor | Annuity | Mutual fund SWP |
Income | Contractual, under the selected option | Withdrawals from your investment |
Longevity | Lifetime options continue while you live | Corpus can become exhausted |
Flexibility | Changes and exits can be restricted | Withdrawals can usually be adjusted |
Inflation | Fixed payments lose purchasing power | Growth potential, without assurance |
Inheritance | Depends on chosen death benefits | Remaining investment passes to beneficiaries |
Tax treatment also differs. Annuity receipts are generally taxable at your applicable slab. For mutual fund redemptions, capital gains taxation applies to the gain component, with treatment depending on fund classification, acquisition date and holding period. Compare spendable income after taxes and applicable charges.
How Should You Compare the Numbers?
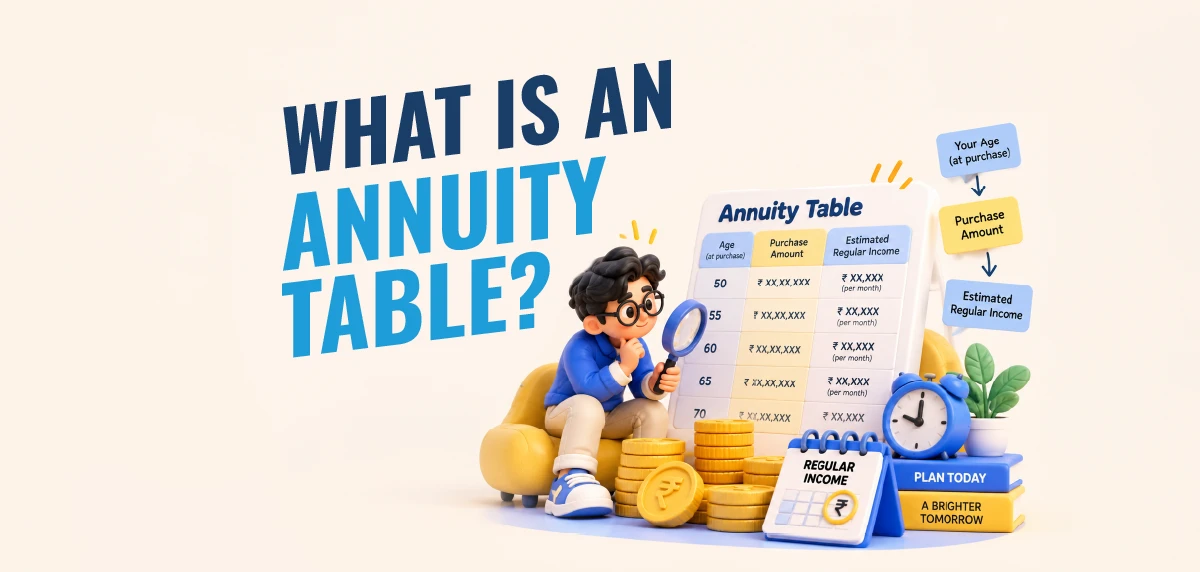
An annuity calculator can estimate payouts using your age, purchase amount and selected benefits. Obtain an insurer quotation before deciding.
An SWP calculator projects withdrawals using assumed returns. Those projections cannot guarantee how markets will behave or how long your money will last.
For illustration, withdrawing ₹30,000 monthly from ₹60 lakh means taking out ₹3.6 lakh annually, an initial withdrawal rate of 6%. That percentage is not a guaranteed return or proof that withdrawals are sustainable.
Inflation changes the requirement further. At an assumed 6% annual inflation, expenses of ₹30,000 become approximately ₹53,725 after ten years. This is an illustration, not an inflation forecast.
Test lower returns, early market losses and rising withdrawals before accepting a projection.
Also compare equivalent benefits: a single-life annuity without purchase-price return should not be judged against an investment projection that assumes your entire original capital remains available to your family after your death.
Should You Use Both?
Your annuity vs SWP decision can begin with essential expenses. Subtract reliable existing pension income from your monthly household requirement. An annuity could help cover part of the remaining gap.
You could retain separate investments for flexible withdrawals, inflation needs and discretionary purchases, while keeping emergency money accessible.
If retirement is still ahead, your annuity planning can also include the IndiaFirst Life Guaranteed Pension Plan, a deferred annuity product offering single-life and joint-life options. Review its premium commitments, income commencement date and policy conditions.
The appropriate balance depends on your pension, dependants, health expenses and willingness to adjust spending.
Before You Go
Monthly income schemes help, but are they sufficient? Estimate your retirement income needs with confidence.
See My Retirement Income
Conclusion
Also consider who will manage your finances when you are older. A withdrawal strategy requiring regular decisions may become harder to maintain, particularly if your spouse handles investments differently. Keep a written income schedule, explain account access and record beneficiary details. Your retirement arrangement should remain usable when managing money becomes less convenient, not merely look attractive on the day you retire.